California's median homeowners association fee is $278 per month, while the national median is $135, and the fee represents about 12% of California's median monthly ownership expenses of $2,232. In Calgary and other Alberta cities, the equivalent condominium contribution is a mandatory owner charge that funds shared operations, long-term reserves, and, when necessary, special levies.
A landlord may discover the problem while preparing a rental listing: the mortgage payment looked manageable, the expected rent appeared competitive, and then the condominium corporation's budget revealed rising contributions, a weak reserve fund, or a pending levy. The monthly fee isn't rent, mortgage interest, property tax, or a utility bill. It's an owner obligation attached to the unit and paid to the condominium corporation for shared property responsibilities.
Table of Contents
- What Is a Homeowners Association Fee
- Understanding Reserve Funds and Special Levies
- How Condo Fees Are Calculated
- Impact on Rental Income and Cash Flow
- Due Diligence for Landlords
- Professional Management Solutions
What Is a Homeowners Association Fee
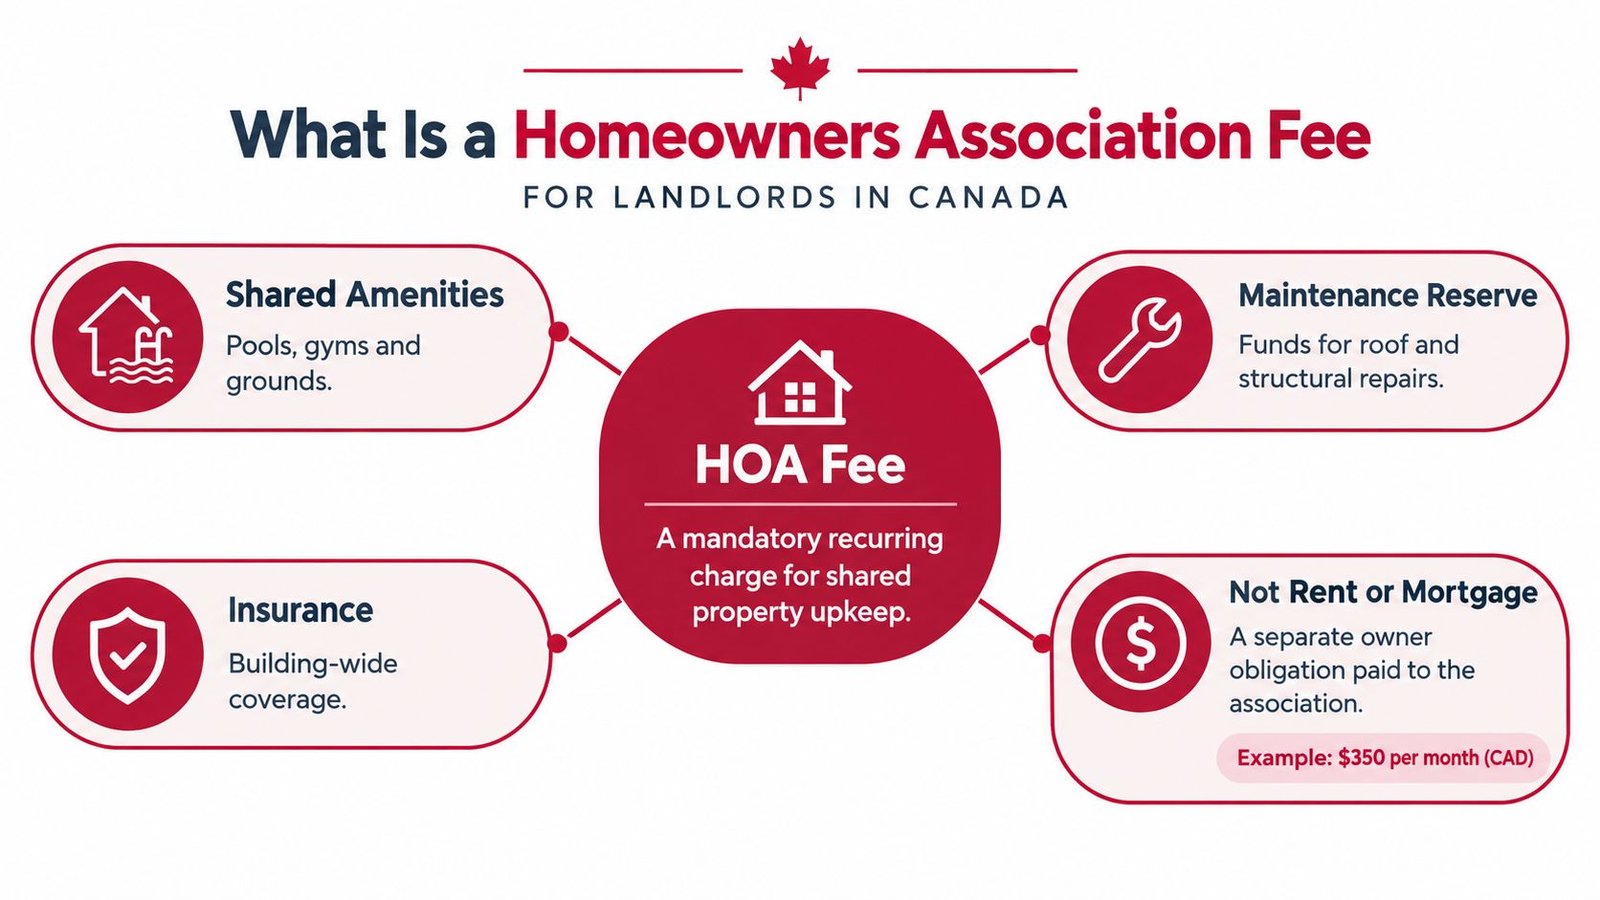
A homeowners association fee, called a condominium contribution in Alberta, is a recurring charge that every condominium owner must pay. The condominium corporation uses it to run and maintain shared property, administer the building, insure common elements, and fund major future repairs. The exact obligations come from the condominium plan, bylaws, budget, contribution schedule, and related governing documents.
For a landlord, this payment belongs in the acquisition and rental analysis from the start. A unit can appear affordable until the corporation's budget shows rising contributions, weak long-term funding, or exposure to a future levy. The charge is separate from rent, mortgage costs, property taxes, and utilities:
- Rent is paid by a tenant under a lease.
- Mortgage payments repay borrowing and interest.
- Property taxes go to the municipality.
- Utilities may be paid by the owner or tenant, depending on the lease.
- Condominium contributions are paid by the owner to the condominium corporation.
The three financial buckets
Operating contributions cover recurring costs such as management, common-area cleaning, landscaping, routine maintenance, insurance, and shared services. They keep the property functioning month by month.
Reserve contributions fund substantial repairs and replacements. The reserve fund may pay for future work on the roof, building envelope, mechanical equipment, elevators, and other common property. Alberta condominium corporations must establish and maintain a reserve fund for major repairs and replacements of common property, managed property, and corporation-owned property, as explained in the Alberta government's reserve-fund guidance.
Special levies are separate charges imposed when operating revenue and reserve funding cannot cover an urgent repair, unplanned expense, or funding gap. For a landlord, that cost can arrive outside the normal monthly schedule and immediately alter the unit's cash flow.
A Calgary example makes the structure easier to test. If the monthly contribution is $420, roughly $300 might support operations and $120 might go toward reserves. The actual split must come from the corporation's budget, not from an assumption based on the headline fee.
Practical rule: A low monthly contribution is not automatically good value. Check whether it funds current services and future obligations honestly.
For an acquisition, record the full contribution as a recurring operating expense. Review reserve information and possible levies separately as indicators of capital risk. That approach prevents rent pricing from relying on an artificially low monthly number.
Understanding Reserve Funds and Special Levies
Two condominium corporations can charge similar monthly contributions while carrying very different financial risks. One may maintain a funded reserve, up-to-date building records, and a credible schedule for major components. The other may keep fees low by postponing necessary work, leaving owners exposed to a sudden special levy. Calgary landlords need to identify that difference before setting rent or buying a unit.
Alberta's reserve-fund system covers major repairs and replacements, not everyday services. Yard work and window cleaning belong in the operating budget. A reserve-fund study examines common-property components, likely replacement timing, estimated costs, and the funds the corporation should hold. The board uses that information to set a reserve-fund plan. A practical guide to reserve funding for condominiums can help landlords interpret the relationship between the study, the plan, and future contributions.
Healthy funding versus deferred cost
A sound contribution structure gives the operating account enough money for recurring obligations while directing an appropriate amount toward long-term capital work. The monthly charge may be higher, but it gives a landlord a clearer cost base and reduces reliance on emergency decisions.
An underfunded corporation can look attractive during a quick purchase analysis. A lower contribution improves the spreadsheet today, yet the apparent saving may represent deferred maintenance. Reserve-fund studies are generally completed every five years under Alberta's condominium framework. Review the latest study and the board's response, not just the headline monthly fee.
A special levy is a one-time or temporary assessment for an unbudgeted expense, operating shortfall, urgent repair, or required reserve increase. After approval, owners must receive information about its purpose, total amount, each unit's share, and the payment date or instalments, as outlined in Alberta's guidance on special levies. For a landlord, that charge can arrive outside the normal monthly schedule and immediately change the unit's cash flow.
What landlords should compare
Place these records side by side:
| Document or figure | What it reveals |
|---|---|
| Current contribution schedule | The owner's recurring obligation and payment timing |
| Operating budget | Whether routine services are properly funded |
| Reserve-fund study | Major components, expected work, and projected costs |
| Reserve-fund plan | How the corporation intends to fund future work |
| Special-levy notices | Immediate or upcoming non-monthly liabilities |
| Board minutes | Repairs, disputes, insurance issues, and unresolved decisions |
A homeowners association accounting guide can clarify the difference between operating transactions, reserve activity, and assessment records.
A low monthly contribution isn't automatically good value. The question that matters is whether the corporation is funding current operations and future obligations in full.
For an acquisition, record the full contribution as a recurring operating expense. Review reserve information and possible levies separately as indicators of capital risk. This keeps rent pricing from relying on an artificially low monthly number.
How Condo Fees Are Calculated
Condominium contributions aren't always divided equally among units. Alberta commonly uses a unit factor, which represents the unit's share of the corporation's costs. The legislation-based calculation normally follows each unit's unit factor unless the Condominium Property Regulation or the corporation's bylaws establish another method. A landlord should therefore read the contribution schedule rather than assume every unit in a building pays the same amount.
The unit factor may reflect the unit's size, ownership interest, or another allocation method set by the condominium documents. The calculation can also account for different ownership interests connected with parking stalls, storage areas, or other components. The exact formula matters because two homes with similar layouts can still carry different contribution obligations.
A practical comparison
Consider two hypothetical units in the same Calgary condominium. Unit A is a smaller interior home with no separately allocated parking component. Unit B appears similar inside but has a larger unit factor and an attached parking entitlement. If the corporation allocates more of the shared budget to Unit B, the two owners won't receive identical contribution statements even though prospective tenants may see them as comparable homes.
That difference flows directly into net operating income. If Unit B rents for the same amount as Unit A but carries a higher monthly contribution, its margin is narrower before accounting for maintenance, insurance, vacancy, financing, or management. The landlord shouldn't respond by assuming the tenant will accept an arbitrary rent premium. Market demand, competing listings, included utilities, parking, condition, and location still determine achievable rent.
Reading the budget properly
The budget should be read in three layers:
- Total corporation costs: Review management, insurance, utilities, repairs, landscaping, and other operating lines.
- Allocation method: Confirm the unit factor, ownership interest, and any separate charges.
- Owner statement: Match the published contribution schedule to the amount charged to the specific unit.
A budget can also show whether the corporation is relying on unusually low routine spending while directing limited money to reserves. That combination may make the current statement look attractive but increase future levy risk. The condo maintenance fees resource provides another useful reference point for connecting fee structure with maintenance responsibilities.
The right question isn't just, “What is the monthly fee?” It is, “What does this unit's contribution pay for, how is the amount allocated, and what obligations remain outside the monthly charge?”
Impact on Rental Income and Cash Flow
For a rental owner, the condominium contribution reduces the income available after operating expenses. It should be included before calculating expected cash flow, not added later as an incidental cost. A property can achieve strong rent and still produce weak net income if the contribution absorbs too much of the revenue or rises faster than the owner's pricing can support.
The first task is to build a complete property budget. Include the current contribution, property taxes, insurance, utilities paid by the owner, management, routine repairs, vacancy allowance, financing, and planned capital spending. Keep regular contributions separate from special levies. The first is a recurring operating cost. The second is a capital or extraordinary cash requirement that can materially change the year's result.
Pricing without overreaching
A landlord can't always pass a contribution increase directly to the tenant. Tenants compare the whole offering, including location, parking, appliances, condition, storage, utilities, pet policies, and move-in terms. A rent increase unsupported by the local market can create vacancy, while a rent held too low can leave the owner subsidizing the unit.
A better approach is to price from evidence and protect the margin through expense control. The owner can review comparable rental listings, identify which services tenants value, and decide whether improvements such as better lighting, paint, storage, or included parking support the target rent. The contribution remains an owner expense even when the tenant benefits from the building's amenities.
Cash-flow discipline: Treat the monthly contribution as variable, not permanent. The corporation can approve increases, change service contracts, or impose a special levy.
Management practices that help
A capable property management process should connect the condominium corporation's activity with the rental ledger. That includes recording contribution invoices, checking payment changes, tracking notices, and filing reserve and levy documents with the unit's financial records. Vendor coordination also matters. A manager who understands the corporation's maintenance responsibility can avoid sending a private contractor to repair an item the corporation should handle, while still acting quickly when the unit owner is responsible.
Reserve monitoring supports acquisition and ongoing ownership decisions. Board communications, budget updates, meeting packages, and levy notices should be reviewed rather than left in an owner's inbox. This is especially important for remote landlords who can't attend meetings or inspect the property regularly.
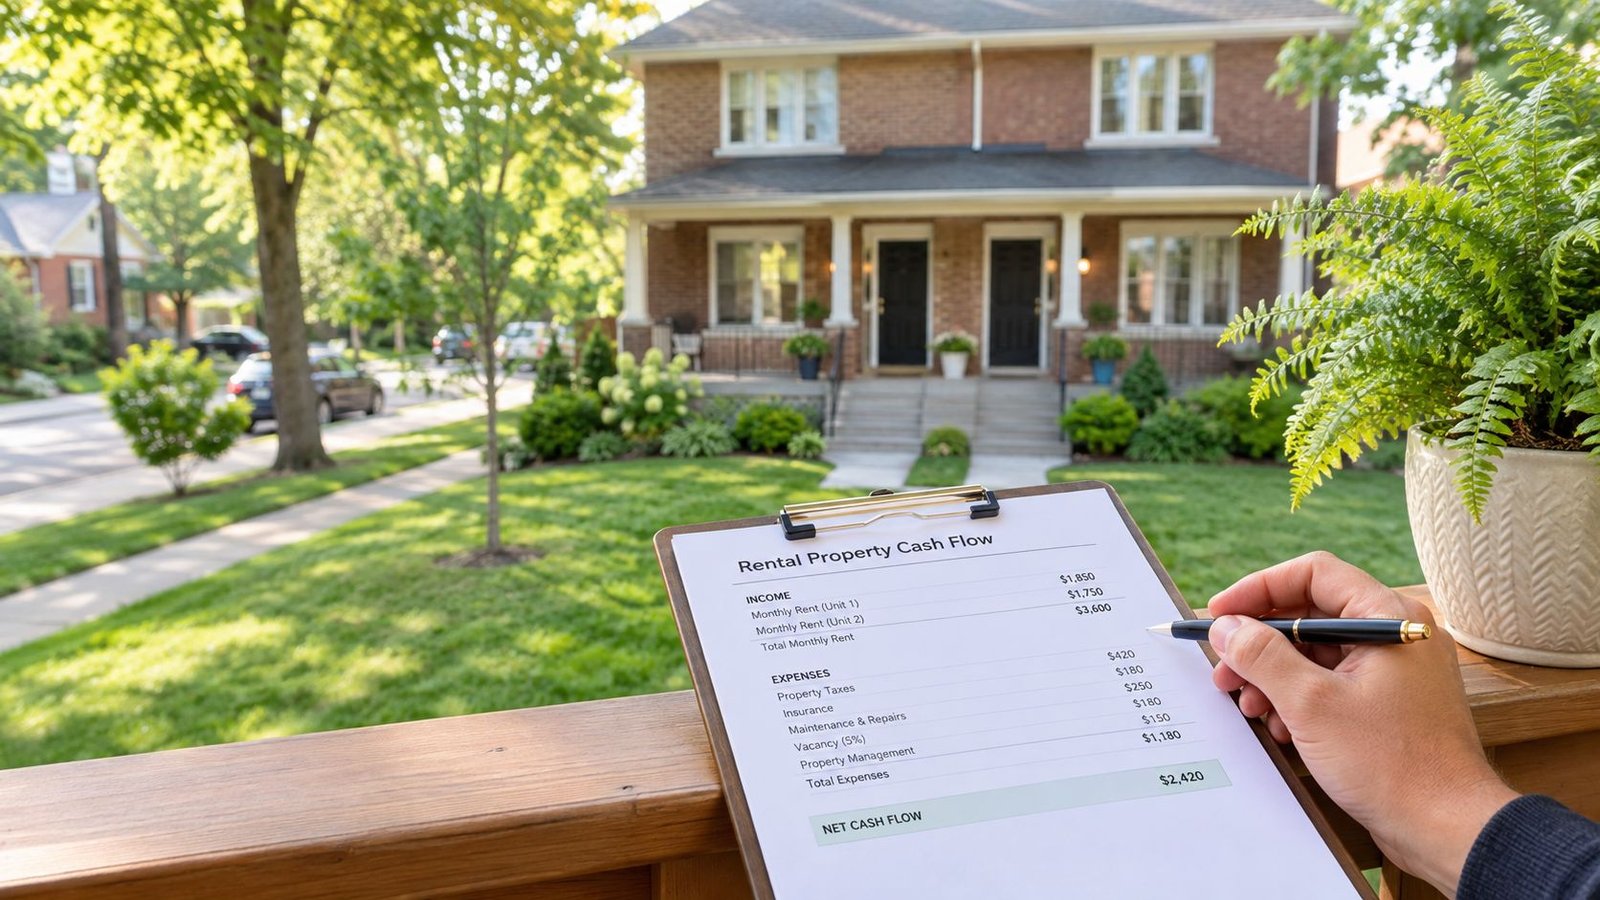
A rental model becomes more resilient when it shows the current contribution, a reasonable allowance for future increases, and a separate plan for extraordinary assessments. That won't eliminate condominium risk, but it makes the risk visible before it damages distributions.
Due Diligence for Landlords
A landlord shouldn't acquire or price a condominium from the listing sheet alone. The listing may show the current contribution, but it won't necessarily disclose reserve weakness, unresolved building work, insurance concerns, or a levy under discussion. Those facts usually sit in the corporation's records.
The acquisition checklist
Start with the current budget and contribution schedule. Confirm what the monthly amount covers, whether utilities are included, how parking and storage are treated, and whether the unit carries any separate charge.
Read the latest reserve-fund study and plan. Look for major components, projected replacement timing, estimated costs, funding assumptions, and recommendations the board hasn't yet implemented. A study is useful only when the contribution plan responds to it.
Review annual reports and financial statements. Compare operating revenue with recurring expenses, examine reserve transfers, and identify unusual reliance on one-time income or deferred work. The objective isn't to chase a perfect balance sheet. It's to understand whether the corporation's budget matches the building's obligations.
Read board minutes and meeting packages. Search for references to water penetration, roofing, elevators, mechanical systems, insurance claims, engineering reports, litigation, owner arrears, and proposed levies. Repeated discussion of the same unresolved repair deserves specific questions before the purchase becomes firm.
Confirm insurance information. Determine what the corporation's policy covers, what the unit owner must insure, and whether deductibles or coverage gaps could affect a rental owner after a loss.
Ask direct levy questions. The buyer should request written confirmation of current, approved, proposed, or anticipated special levies. The purchase agreement and closing process should clearly address responsibility for amounts imposed before or after the relevant date.
Why the file review matters
A landlord is underwriting more than the interior unit. The investment includes a share of a corporation that owns or manages common property, hires contractors, carries insurance, sets budgets, and makes repair decisions. A clean unit with a weak corporation can create more financial uncertainty than an older unit with a well-organised reserve plan.
Red flag: A corporation that can't produce clear budgets, current reserve information, or consistent meeting records deserves deeper investigation before the owner relies on its contribution as predictable.
The same checklist applies when taking over an existing rental. A manager should collect the records, verify the payment account, update the owner's budget, and establish a process for forwarding every condominium notice.
Professional Management Solutions
Condominium ownership creates a second operating relationship alongside the tenant relationship. The landlord must satisfy the lease, maintain the private unit, respond to tenant issues, and also monitor a corporation that controls shared property and imposes owner charges. That administrative overlap is where missed notices, incorrect repair assignments, and poor cash-flow forecasts often begin.
Professional management adds value by turning scattered condominium information into a controlled operating file. The manager can record the current contribution, reconcile invoices, track changes against the approved budget, and flag unusual charges before the owner's statement is prepared. When a special levy notice arrives, the manager can identify the purpose, payment terms, unit allocation, and likely effect on the rental forecast.
Where coordination makes a difference
A property manager can also coordinate vendors around responsibility lines. If a leak involves a common element, the corporation may need to direct the repair. If damage is inside the unit, the owner or insurer may be responsible. Clear communication with the board, building manager, insurer, tenant, and contractor prevents duplicated work and reduces delays.
The owner still makes the investment decision, but professional oversight supplies the documentation needed to make it well. The manager can request meeting packages, maintain reserve-fund records, follow board communications, and ensure the tenant receives practical instructions without being burdened with the owner's financial obligations.
Landlords comparing software and workflow options may find a guide to HOA management platforms useful for understanding document tracking, communications, and association administration. Technology helps organise records, but it doesn't replace judgement. Someone must read the budget, recognise a recurring repair concern, and explain what it means for rent and cash flow.
Owners who want a structured operating process can review condo property management services for support with tenant placement, rent collection, inspections, maintenance coordination, owner reporting, and condominium communication. The practical benefit is not just convenience. It is better visibility into the expenses and decisions that shape the unit's actual return.
Dreamhouse Realty Ltd. helps Calgary and surrounding Alberta landlords manage condominium rentals through tenant placement, rent collection, inspections, maintenance coordination, compliance support, and owner reporting. Contact GURIQBAL CHAHAL, MBA, PMP, REAL ESTATE BROKER at 403-966-6072 to review a condominium budget, assess fee and levy risk, and discuss a management plan, or visit Dreamhouse Realty Ltd. for more information.